

Part One of The Good, The Bad & The Digital
By Alia Noor, FCMA, CGMA, MBA
UAE Registered Tax Agent | Associate Partner – Taxation & Compliance Advisory
Ahmad Alagbari Chartered Accountants
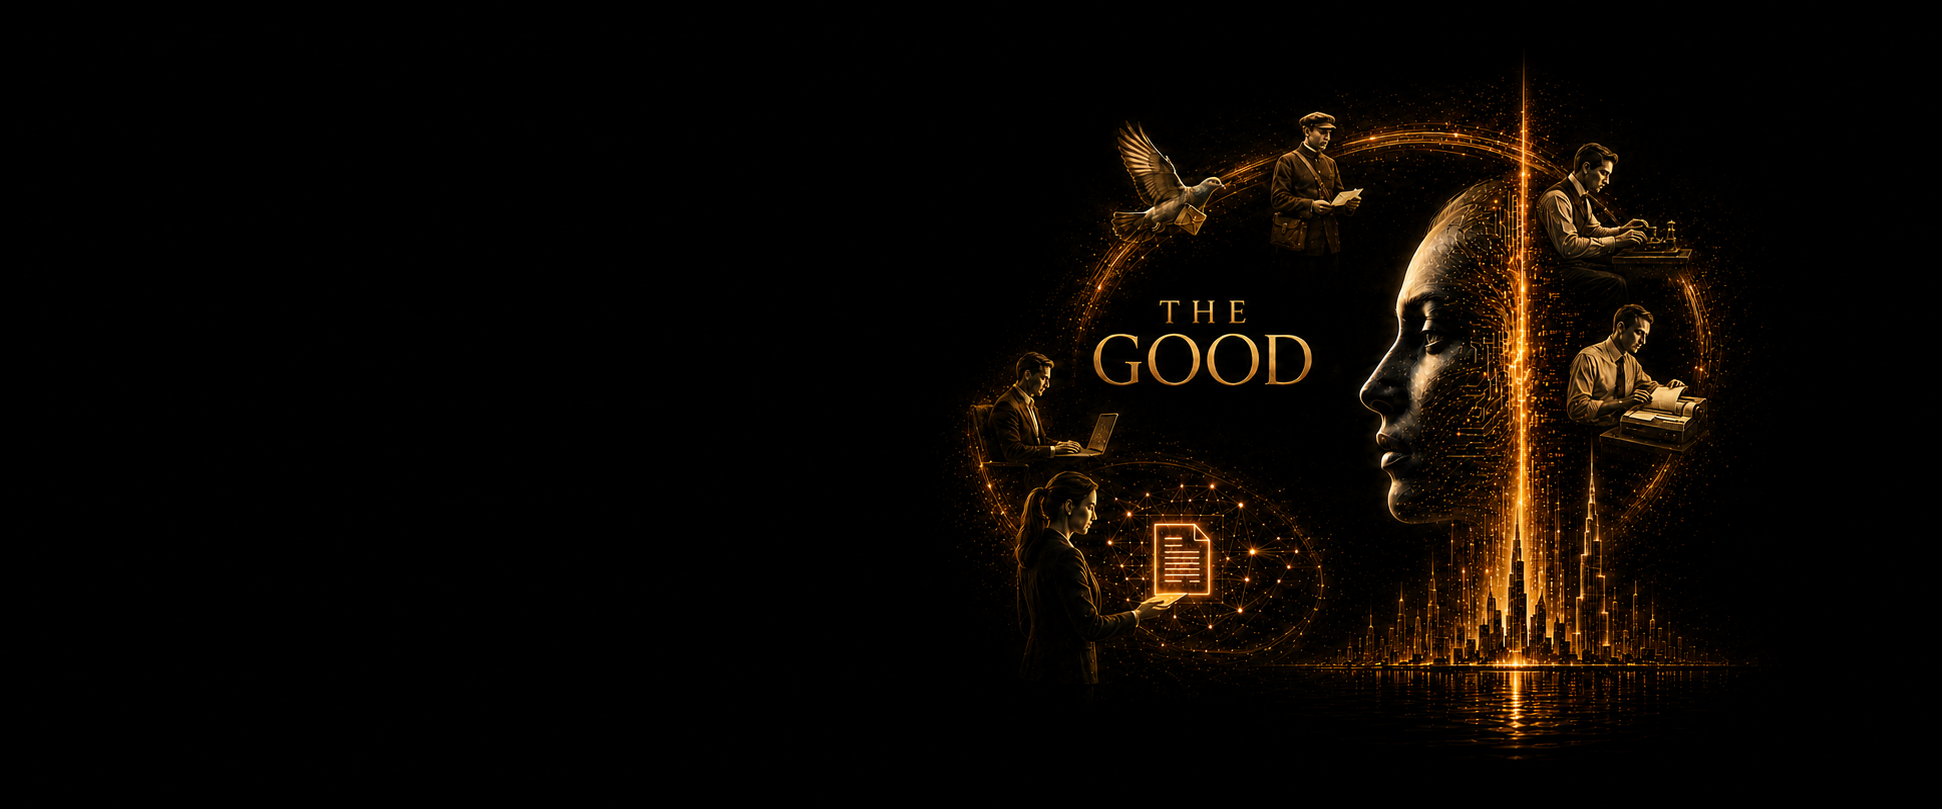
There was a time when a message travelled on the leg of a pigeon.
Later, documents crossed countries inside postal bags. The telegraph allowed words to travel without paper. Fax machines delivered copies directly into offices, and email reduced the journey to a single click.
With every invention, distance became less important and delivery became faster.
But the invoice’s journey never truly ended when it arrived.
Someone still had to open it, understand it, enter its information, check its accuracy and move it towards payment. A document could cross the world in seconds—and then wait for weeks inside the wrong inbox.
UAE eInvoicing begins where every earlier invention stopped.
It allows structured invoice data to enter the buyer’s system, undergo technical validation and continue through the business process.
The destination is no longer the inbox.
The destination is action.
The PDF Was Only Half the Revolution
Businesses believed emailing a PDF meant invoicing had already become digital. The paper disappeared, but people continued downloading attachments, entering figures, checking totals and forwarding documents.
The UAE Ministry of Finance is clear: a PDF, Word document, image, scanned copy or email is not an eInvoice. An eInvoice is issued, transmitted and received in a structured electronic format that enables automatic and electronic processing.
From Peppol to Process
Under the UAE’s five-corner model, the supplier sends invoice data through a UAE Accredited Service Provider. The provider validates and transmits the eInvoice to the buyer through the buyer’s provider, while prescribed tax data is reported electronically.
The buyer’s provider performs its required validation and delivers the invoice to the buyer’s system. Status messages indicate whether the invoice was successfully exchanged and reported; they do not mean the buyer commercially approved it.
When “Sent” Finally Means Something
Today, “invoice sent” may mean little more than “email delivered.” It does not prove that the invoice reached accounts payable, entered the approval process or contained the information required by the buyer.
EInvoicing replaces some of that uncertainty with evidence. If prescribed information is missing or technically invalid, the problem may become visible during the exchange rather than weeks later.
A rejected invoice can be corrected.
An invisible invoice cannot.
EInvoicing cannot force a customer to pay or prevent a commercial dispute. Where procurement and finance systems are connected, however, invoice data may be matched against a purchase order and evidence of receipt.
Transactions meeting the buyer’s rules can progress, while genuine exceptions are directed to employees for review. The invoice has not simply arrived faster; it has arrived in a form capable of moving forward.
Better Data, Earlier Answers
Structured invoice data can reveal recurring errors, approval bottlenecks and collection problems. Finance can distinguish an invoice that failed during exchange from one delayed after successful delivery and direct each problem to the right team.
The Ministry of Finance also expects eInvoicing to facilitate the pre-population of certain VAT-return fields and expedite refund processing. However, the business remains responsible for the VAT treatment, supporting evidence, reconciliations and its return.
Technology can identify incomplete or inconsistent data.
It cannot make an incorrect tax decision correct.
Three Phases, One Opportunity
In-scope persons with revenue of AED 50 million or more must appoint an Accredited Service Provider by 30 October 2026 and implement eInvoicing by 1 January 2027.
In-scope persons below AED 50 million must appoint a provider by 31 March 2027 and implement by 1 July 2027. In-scope government entities must appoint a provider by 31 March 2027 and implement by 1 October 2027.
Before selecting technology, businesses should examine whether their customer records, invoice fields and tax classifications contain the information the new system will require.
One organisation will purchase a technical connection and preserve its manual processes. Another will improve its data, connect finance and procurement, strengthen controls and gain better visibility over collections.
Both may comply.
Only one will transform.
After the Pigeon
The pigeon gave the message wings. The postal service gave it reach. The telegraph, fax and email gave it speed.
PINT AE gives the UAE invoice a structured language, while the OpenPeppol framework gives it an interoperable route and the ability to continue moving after delivery.
For centuries, businesses improved the messenger.
Now they can improve the message—and everything that happens after it arrives.
That is The Good.
But when every required field matters, poor data can no longer hide quietly inside a PDF.
That is where The Bad begins.
Disclaimer
This article is for general informational purposes only and does not constitute legal, tax, accounting or technology advice. UAE eInvoicing requirements continue to evolve. Businesses should refer to the latest legislation and official Ministry of Finance and Federal Tax Authority guidance and obtain professional advice relevant to their circumstances.
Official references: UAE Ministry of Finance eInvoicing portal, MoF deadline amendment and MoF phased implementation announcement.

Leave a Reply